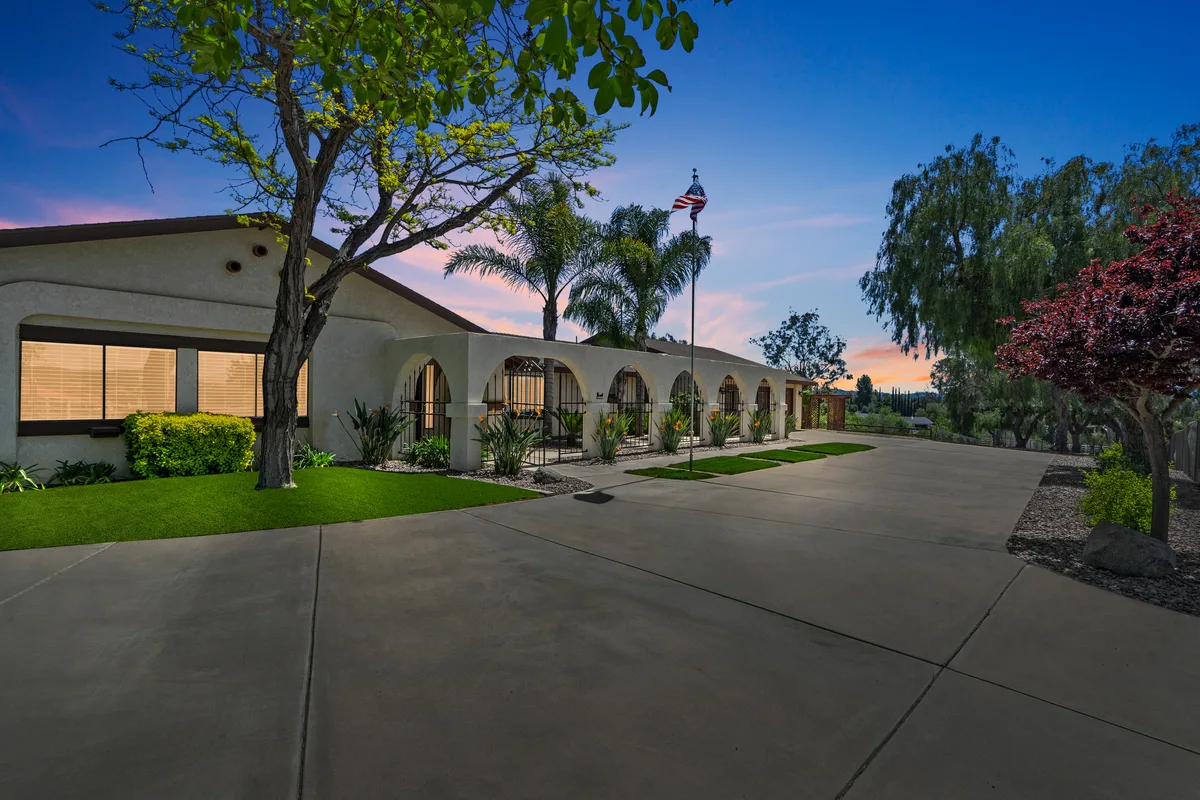
When escrow opens, the lender orders an appraisal. It is an independent, professional estimate of a home’s market value, prepared by a licensed or certified appraiser, and it exists to protect the lender: it confirms the home is worth what the buyer agreed to pay before a bank lends against it.
Your agent is not the one who decides the value, and neither is the seller. That is the first thing to understand about an appraisal, and why it sometimes surprises people. Laura and Cheryl have walked clients through appraisals many times, and their advice is the same for both sides: understand how it works before it happens, so the result never feels like a crisis.
What Is an Appraisal, and How Is It Different From a CMA?
You will hear two words during a home sale that sound alike but are not: appraisal and CMA. A broker-prepared Comparative Market Analysis (CMA) is what we use to help you understand a home’s likely market value and set a listing price or a strong offer. It is an analysis, not a formal valuation.
An appraisal is a separate, documented valuation completed by an appraiser, and it is usually tied to your financing. Both can reference similar nearby sales, but they serve different purposes, and the number they land on can differ. The two numbers can differ.
Buyers typically pay for the appraisal as part of closing costs, and the cost is included on your loan estimate. For a deeper look at the fees on your side, our guide to closing costs for California buyers breaks down what to expect.
How the Appraisal Fits Into Escrow
Once your offer is accepted and escrow opens, the lender orders the appraisal, usually well before the closing date. The appraiser visits the home, measures it, reviews its condition, features, and lot, and compares it against recent sales of similar homes nearby. For a full look at this phase of your transaction, see what happens during escrow in California.
Every loan program has its own rules. An FHA appraisal also checks that the home meets minimum health and safety standards, not just market value. A VA appraisal has its own requirements tied to the VA’s Minimum Property Requirements. Conventional appraisals focus primarily on value.
Why a Home Can Appraise Lower Than the Agreed Price
This is the scenario buyers and sellers worry about most, so let us talk about it honestly. If the agreed price is higher than the appraised value, the lender will base its loan on the lower number. Nothing about the house is wrong, and no one has done anything careless. It simply means the sale price and the appraiser’s estimate of market value did not line up.
- It happens in competitive markets. When multiple offers push a price above what recent sales support, an appraisal can trail the contract price, especially on a fast-moving listing.
- Comparables drive the number. The appraiser uses the most recent, most similar sales available. If few comparable homes have sold nearby, the estimate can be conservative.
- Condition matters. Deferred maintenance and dated features can weigh on an appraisal even when demand for the area is strong.
A low appraisal is not the end of the road.
What Happens When There Is an Appraisal Gap
When an appraisal comes in below the contract price, the buyer, the seller, and both agents talk through the options. Depending on the contract and the situation, the path forward might include any of these:
- Renegotiate the price. The buyer and seller can agree to a new price at or closer to the appraised value.
- Bridge the gap. A buyer may choose to bring additional cash so the down payment still meets the terms of the agreement.
- Challenge the appraisal. If the appraiser missed important details or comparable sales, your agent or lender can request a review with supporting evidence.
- Walk away, if the contract allows. Most purchase agreements include a financing or appraisal contingency that lets a buyer exit if a home truly cannot be financed at the agreed terms.
Which path fits depends on the appraisal number, how much cash the buyer can bring, and what both sides want. That is exactly why our team’s approach is negotiating more than the price: we help buyers and sellers weigh the real choices.
How an Appraisal Gap-Addendum Can Protect You
In a competitive market, some buyers include an appraisal gap addendum or contingency waiver to make their offer more attractive. This can strengthen a buyer’s position against competing offers, but it also changes the risk. Before you agree to one, we make sure you understand exactly how much of a gap you could be responsible for and whether that fits your budget. We would rather you feel calm and prepared than surprised later.
For sellers, the way to reduce appraisal surprises is pricing with evidence from the start. Our guide on pricing your home right explains why the first weeks on market and the initial price matter so much, and our article on what your home may really be worth walks through the valuation side.
Why an Appraisal Is Not the Same as an Inspection
An appraisal and a home inspection are two different checks, and both matter. The appraisal is about value for the lender. An inspection is about condition, and it is for you: it looks for defects, safety issues, and systems that may need repair. A home can appraise at full value and still have things an inspector recommends fixing, which is why we always encourage an inspection in parallel with the appraisal process.
One common mistake we see is sellers making costly renovations believing they will automatically raise the appraised value. Improvements can help a home compete and support value, but the amount spent does not automatically become the amount added. Our home valuation FAQ addresses this and many other valuation questions honestly.
How Our Team Handles Appraisals With You
When you work with Laura and Cheryl, an appraisal is never a mystery. Before it happens, we explain how the visit and the report work. During it, we make sure you know what the appraiser is likely to weigh. And if the result surprises anyone, we guide the conversation with facts, options, and no pressure.
Whether you are buying, selling, or simply wondering what your home is worth, our goal is the same: help you feel confident from start to finish. If you are curious about your own home’s position in the Murrieta, Temecula, or Menifee market, a free, no-obligation valuation is a great first step. You can learn more about us on our About page, or just start a conversation. We will talk later.
Have Questions About an Appraisal or Home Value?
Whether you are buying, selling, or just wondering what your home is worth, Laura and Cheryl will explain the process clearly and help you make a calm, confident decision. No pressure, just honest guidance.
Laura Holbert · CA DRE# 01932682 · Cheryl Shadden · CA DRE# 01932888
Related Resources
Laura Holbert
Realtor/Broker · CA DRE# 01932682 · Accredited Buyer’s Representative (ABR)
(951) 704-4635 · Laura@TeamIntegrityRealty.com
Cheryl Shadden
Realtor/Broker · CA DRE# 01932888 · Accredited Buyer’s Representative (ABR)
(951) 285-1245